Why LandAndCreek Offers a Smarter Path to Rural Land Ownership 64733
The Real Challenge of Buying Rural Land
I have spent years helping people find the right piece of rural property. One thing that always stands out is how many buyers assume they need perfect credit and a huge down payment to own land. That belief keeps a lot of good people stuck renting or living in places they do not love. The truth is that rural land ownership has always been more accessible than most people think, but the traditional lending system does a poor job of making that clear.
When you look at land sales through a conventional mortgage lender, you hit a wall quickly. Banks treat raw land as high risk. They ask for 30 to 50 percent down, charge higher interest rates, and demand a credit score that many hardworking people simply do not have. That model works for someone buying a house in a subdivision. It does not work for someone who wants a few acres for a weekend cabin or a place to park an RV while they build slowly.
That is where owner financing changes everything. A seller who offers financing directly cuts out the bank. They set their own terms. They care more about whether you will take care of the land than about your FICO score. And for the buyer, that means a real chance to own something without jumping through impossible hoops.
What Owner Financing Actually Looks Like
Owner financing means the seller holds the note. You make payments directly to them instead of to a bank. The property itself secures the loan. If you stop paying, the seller takes the land back. That simplicity is why it works for people who would never qualify for a conventional loan.
I have seen buyers with credit scores in the low 500s close on beautiful pieces of rural land through owner financing. They paid a modest down payment, agreed to a reasonable interest rate, and made monthly payments that fit their budget. No one checked their credit. No one asked for tax returns. The seller just wanted to know that the buyer understood the responsibility and had a steady income.
The trade-off is that owner financed land usually costs a bit more in total interest than a conventional loan would. But that extra cost is often worth it when the alternative is not owning land at all. You also get a faster closing process. No appraisal. No underwriting. No waiting weeks for a bank to approve something. If both parties agree on terms, you can close in a matter of days.

Finding the Right Piece of Land
Not all rural land is created equal. Some parcels look cheap on paper but have no road access, no legal right to build, or terrible soil for a septic system. I have walked properties that seemed perfect in the listing but turned out to be swampy half the year. You have to do your homework before you buy.
Start by asking about access. Does the land have a recorded easement? Is there a road to the property line? If the only way in is across a neighbor's field, you need a legal right to cross it. Verbal permission is not enough. Get it in writing.
Next, check the zoning. Rural counties have rules about what you can do with land. Some allow tiny houses. Some require a minimum square footage for a dwelling. Some ban RVs as permanent residences. You need to know those rules before you commit to a payment plan.
Water and sewer are the next big questions. Can you drill a well? Is there a septic permit available? In some areas, the soil percolation test is the hardest part of building. If the ground does not drain well, you may not get a permit. That can kill your plans to build anything permanent.
When you look at land through a platform like landandcreek, you get a lot of those details upfront. The listings include information about access, utilities, and zoning. That transparency saves time and prevents buyers from falling in love with a property that will not work for their needs.
Why People Choose Rural Land Now
The pandemic shifted how people think about space. Suddenly, a small apartment in a crowded city felt like a trap. People started looking for room to breathe. They wanted a place where they could garden, hunt, or just sit outside without hearing traffic. Rural land became more than a weekend escape. It became a long-term strategy for freedom and security.
I talk to buyers every week who want land for recreation. A hunting cabin in the woods. A spot to park an ATV and ride trails. A piece of riverfront where they can fish on summer mornings. Those are simple dreams, but they require a place to put them. Owner financing makes those dreams possible without going into debt to a bank.
Other buyers are planning for off-grid living. They want solar panels, a composting toilet, and a rainwater catchment system. They do not want a mortgage that forces them to work a job they hate just to pay the bills. Rural land gives them that option. They can buy a small parcel outright with a low down payment, then build slowly as they save money.
And then there are the legacy builders. These are the people who buy land not just for themselves but for their kids and grandkids. They want a place where the family can gather for generations. A piece of land that stays in the family long after the original buyer is gone. Owner financing lets them start that legacy without waiting until they have perfect credit or a huge pile of cash.
What to Look for in a Seller
Not all owner financing deals are fair. Some sellers offer terms that look good at first but hide traps. A high interest rate. A balloon payment after a few years. A prepayment penalty that makes it expensive to pay off the loan early. You have to read the contract carefully.
A good seller will be transparent about the terms. They will explain the interest rate, the loan term, and whether there are any penalties for paying early. They will show you a sample amortization schedule so you can see how much of each payment goes to principal versus interest. They will answer your questions without pressure.
I have seen sellers who genuinely want to help people get into land. They offer reasonable rates and flexible terms. They understand that a buyer who feels good about the deal is more likely to make payments on time. That kind of seller is worth working with.
On the other hand, I have seen sellers who treat owner financing as a way to flip properties quickly. They charge high interest and expect a default so they can take the land back and sell it again. You can avoid those sellers by asking for references and checking if they are willing to provide a simple, clear contract.
Making the First Move
The hardest part of buying rural land is getting started. People dream about it for years but never take the first step because they assume it is out of reach. The truth is that you can start with a small down payment and a modest monthly payment. You do not need to buy 40 acres right away. Start with five or ten. See how it feels. You can always buy more later.
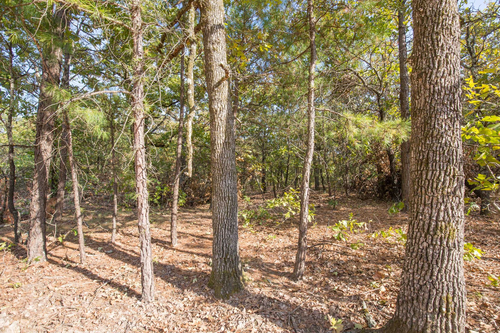
When you browse through a site like landandcreek, you will see parcels that fit different budgets and goals. Some are perfect for a weekend tent camp. Others have enough room for a small house and a garden. The key is to find a property that matches what you actually want to do with it, not what you think you should want.
Talk to the seller. Ask questions about the land. If you can, visit the property before you buy. Walk the boundaries. Look at the neighbors. Get a feel for the area. That investment in time will pay off when you find a piece of land that feels like yours.
Owner financing is not a shortcut. It is a different path. One that works for people who are willing to take responsibility for their own future. If you are ready to own land and build something real, there is no reason to wait. The right parcel is out there, and the terms can work for you.
