Finding Your Own LandAndCreek: A Practical Guide to Rural Property Ownership
For years I watched friends sink their savings into suburban houses with HOAs, shared walls, and zero privacy. They paid for lawns they could not keep and views of the neighbor's fence. Meanwhile, I was looking at maps of rural counties, dreaming about a piece of ground where the only sound at night was frogs and running water. That search eventually led me to the idea of owner-financed land, a path that felt less like a mortgage trap and more like a handshake between people who understood the value of space.
What I found surprised me. You do not need perfect credit to buy rural property. You do not need a massive down payment. What you need is patience, a clear idea of what you want the land for, and a willingness to look past the glossy listings to see what a place actually offers. That is where a resource like landandcreek becomes useful, not as a sales pitch but as a practical tool for matching people with ground they can actually afford.
Why Owner Financing Changes the Game
Conventional lenders treat raw land like a bad bet. No house means no occupancy, no occupancy means lower appraisal values, and lower values mean higher risk in the bank's eyes. So they demand 30 or 40 percent down and they charge interest rates that make you wonder if the loan officer is trying to talk you out of it. Owner financing sidesteps the whole banking apparatus. The seller carries the note, you make payments directly to them, and the terms are negotiated between two people who both want the deal to work.
I have seen deals where the down payment was less than a month's rent in a city apartment. I have seen sellers who would rather carry a small note at a fair rate than sit on the land for another year paying taxes and mowing. That flexibility is real. It is not a marketing gimmick. It is the result of sellers who understand that a willing buyer with a steady job is better than no buyer at all.
What to Look For in Rural Land
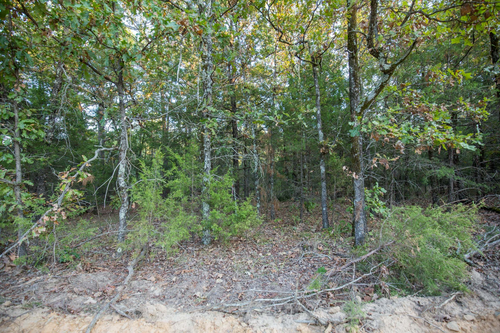
When you start looking at properties, the photos can be deceiving. A wide-angle shot of a meadow can hide the fact that the only legal access is a two-track that turns to mud in October. A creek running through the property sounds idyllic until you check whether you can actually build within the floodplain setback. Here are the things I have learned to verify before making an offer:
- Legal access: a recorded easement or deeded road frontage, not just a neighbor's permission.
- Water rights: does the creek belong to you, or is it subject to senior claims?
- Soil quality: percolation tests for septic, because a failed perc test can kill a building plan.
- Zoning and covenants: can you park an RV, keep livestock, or build a cabin without a fight?
- Tax status: some rural counties have back taxes that become your problem at closing.
None of these are dealbreakers on their own, but they are the kind of details that separate a good buy from a money pit. When I first started looking, I skipped half of these checks and nearly bought a parcel that had no legal water source. The seller was honest about it, but only after I asked directly.
The Appeal of Water and Trees
I keep coming back to properties that include a creek or a river frontage. There is something grounding about having moving water on your land. It draws wildlife, it moderates the temperature in summer, and it gives you a reason to walk the property line every season. But creeks also bring responsibility. You need to understand flood zones, erosion control, and in some states, streamside buffer regulations that limit how close you can build.
One property I looked at had a beautiful spring-fed creek running through the middle of it. The water was clear, cold, and full of crayfish. But the floodplain maps showed that half the buildable area was inside the 100-year flood zone. That did not rule out the property, but it meant the house would have to sit on the high ground near the road, not down by the water where I had imagined it. Knowing that before I bought saved me from an expensive mistake.
Sites like landandcreek often list these details in the property descriptions, but you should still verify everything with local records. The listing might say "seasonal creek" when the water runs only after heavy rain, or it might say "pond" when the pond is actually a catchment basin that goes dry by August. Ask questions. Visit in the spring when the water table is highest. That is when you see the real character of the land.
Building a Legacy on Raw Land
The phrase "building a legacy" gets thrown around a lot in real estate marketing, but for rural land it actually means something. You are not flipping a house in two years. You are buying a piece of ground that could stay in your family for decades. Maybe you put in a cabin now and add solar panels later. Maybe you clear a trail system for four-wheeler rides and hunting access. Maybe you just hold it as a place to camp and escape the noise of town.
I know a man who bought forty acres in the Missouri Ozarks with owner financing. He paid it off in ten years, then helped his son buy the adjoining parcel the same way. They now have a hundred contiguous acres that they hunt, hike, and eventually plan to build on. That kind of continuity does not happen with a thirty-year bank mortgage. It happens when the barrier to entry is low enough that ordinary people can take the first step.
Practical Steps to Get Started
If you are serious about buying rural land, start by getting clear on your budget and your goals. Do you want recreational land for camping and hunting, or are you planning to build a full-time residence? The answer changes the kind of property you need. Recreational land can be steeper, more remote, and have fewer utilities. Residential land needs road access, power nearby, and a perc test that passes for a septic system.
Once you know what you want, start watching listings on a site like landandcreek. Look at properties that have been listed for a while. Sellers who have been carrying a note for months are often more willing to negotiate on price or terms. Do not be afraid to make an offer that feels low. The worst they can say is no, and you might be surprised how often they say yes.
When you find a property that interests you, walk it end to end. Bring a GPS or a phone with offline maps. Mark the boundaries if they are not obvious. Take photos of the corners and the monuments. Talk to the neighbors if you can. They will tell you about flooding, road maintenance, and wildlife patterns faster than any real estate agent will.
Finally, get everything in writing. The seller might be a good person, but memories fade and circumstances change. A simple contract that spells out the payment schedule, interest rate, default terms, and who pays the taxes will save you years of headaches. I have seen handshake deals go bad when the seller died and the heirs did not honor the verbal agreement. Paper protects both sides.
Living the Land Life
Owning rural land is not for everyone. It requires work. There are fences to mend, weeds to cut, and long drives to get groceries. But the trade-off is a kind of freedom that is hard to find in town. You can build a fire without a permit. You can walk outside in your bare feet and not see another person. You can teach your kids where food comes from and how to read a topo map.
I have never regretted buying my piece of ground. It is not perfect. The creek floods some years. The road needs grading after every big rain. But when I sit on the porch at dusk and watch the bats hunt over the water, I know I made the right choice. And I did it without a bank looking over my shoulder, without a credit check, and with a down payment that did not wipe out my savings. That is the kind of deal that changes your life.
