Finding Freedom: Why LandAndCreek Offers a Smarter Path to Rural Land Ownership
Owning a piece of rural land is a dream that sits deep in the American psyche. It is about having a place to breathe, to build, and to pass down. But for many people, that dream hits a wall when they face traditional financing. Banks want perfect credit, large down payments, and a quick path to a house. They are not set up to sell you a few acres of woods where you plan to put a camper and a fire pit. That is where a different kind of land buying experience comes in, one that focuses on the land itself and your ability to pay over time.
I have spent years working with people who are looking for that kind of freedom. They are not speculators or developers. They are electricians, teachers, nurses, and retirees who want a weekend spot to hunt, a place to park an RV, or a piece of ground where they can eventually build a small cabin. The common thread is that they are tired of being told no. They have the income to make a payment, but their credit score does not tell the whole story. That is where owner financing changes everything.
What Owner Financing Really Means for You
When a seller offers owner financing, they are acting as the bank. Instead of you going to a lender and qualifying for a mortgage, you make payments directly to the seller. The terms are set between you and them, not by a loan officer in a distant office. This opens the door for people who have been through a bankruptcy, have a thin credit file, or simply prefer to avoid the paperwork circus of a conventional loan.
I have seen people assume that owner financing is always a bad deal, that the interest rates must be sky high or that the seller can take the land back at any moment. In reality, many owner-financed deals are fair and transparent. The seller is motivated to keep you as a buyer because they want the land to sell, not to repossess it. They are also willing to work with you on down payments that are much lower than what a bank would demand. Some sellers ask for as little as five or ten percent down. That makes the difference between buying now and waiting another five years.
There is also the matter of credit checks. Many traditional lenders run a hard pull on your credit, which can ding your score. With owner financing, the seller often does not run a credit check at all. They care more about whether you can make the monthly payment and whether you are serious about the property. This approach respects the fact that your past credit problems do not define your future ability to pay.
Rural Land for Recreation and Off-Grid Living
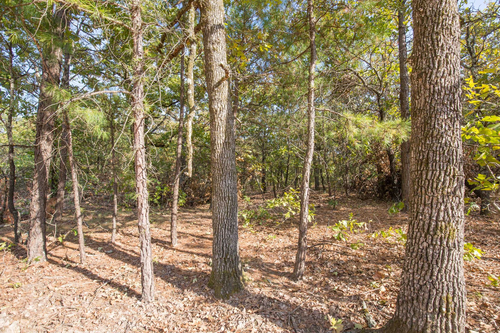
The properties available through platforms like landandcreek are not suburban lots with utilities already stubbed in. They are rural acres, often wooded, sometimes with a creek running through them, and frequently without power or water at the lot line. That might sound like a drawback, but for many buyers it is exactly the point. They want to be off the grid, at least for part of the year. They want to set up a solar panel, haul in water, and live simply for a few days at a time.

I have helped families find land where they could park a travel trailer and spend the summer weekends. I have seen hunters buy a forty-acre parcel just for deer season, then later decide to build a permanent stand. The land does not have to be developed to be valuable. It just has to be yours. That sense of ownership, of having a place where you can walk your own ground and hear nothing but wind and birds, is something that a suburban backyard cannot replace.
Off-grid living does not mean roughing it forever. Many people start with a tent or a camper, then gradually add infrastructure. They put in a gravel driveway, then a well, then a small shed. Over time, the land becomes a home base. The beauty of owner financing is that you can start using the land immediately, even while you are still paying it off. You are not waiting for a bank to release funds or for a builder to finish a house. You buy the land, and it is yours to enjoy from day one.
Building a Legacy Without Breaking the Bank
One of the most compelling reasons to buy rural land is the chance to build something lasting. A piece of land can be a legacy asset, something you pass to your children or grandchildren. It does not depreciate like a car or a boat. Over time, land tends to hold its value and often appreciates, especially if it is in a desirable area near recreation or growing towns.
But you do not need a huge inheritance to get started. With low down payments and no credit check, a buyer can secure a parcel for a few thousand dollars down. That is less than the cost of a used car. And unlike a car, the land is not going to rust or wear out. It is a tangible asset that you can see, walk on, and improve at your own pace.
I have seen families buy a small parcel, then over the years add more acreage next door. They start with a weekend spot and end up with a family compound. That kind of growth is possible because the initial purchase was affordable and the terms were manageable. The seller wants you to succeed, partly because a successful buyer is more likely to pay on time and partly because they take pride in seeing the land used well.
What to Look for When Buying Owner-Financed Land
Not every deal is a good deal, and it pays to do your homework. Here are a few practical things to check before you sign anything.
- Access. Make sure there is a legal right of way or a road that gets you to the property. Some rural parcels are landlocked, which means you cannot reach them without crossing someone else's land. A written easement is essential.
- Zoning and restrictions. Find out what the county allows. Can you park an RV there? Can you build a permanent structure? Some areas have minimum square footage requirements or setbacks that can complicate your plans.
- Utilities. Even if you plan to go off-grid, it helps to know if power, water, or internet are available nearby. You might want to tap into them later. Check with the local utility companies.
- Survey. A recent survey shows exactly where the boundaries are. Without one, you could accidentally build on a neighbor's land or think you own more than you do.
- Payment terms. Read the contract carefully. Understand the interest rate, the length of the loan, and what happens if you miss a payment. Some contracts have a balloon payment after a few years, so you need to plan for that.
These steps are not meant to scare you. They are just the basics of any land purchase. A good seller will be happy to answer these questions and provide documentation. If they dodge or hesitate, that is a red flag.
How LandAndCreek Fits Into the Picture
When you look at a site like landandcreek, you are seeing properties that are specifically marketed to people who want owner financing. The listings are curated to show you the details that matter: price, down payment, monthly payment, acreage, and location. The seller has already decided to offer terms that work for buyers without perfect credit. That saves you the trouble of finding a seller who is willing to finance, which can be a long and frustrating search on your own.
I have walked through listings on landandcreek with buyers, and what stands out is the variety. There are small lots that are perfect for a weekend tent setup, and larger tracts that could support a full homestead. The site makes it easy to filter by state, price range, and acreage. You can get a feel for what is available without having to call around to dozens of individual sellers.
The process is also straightforward. You find a property you like, contact the seller through the site, and negotiate the terms. There is no middleman lender, no loan officer, no credit check. You and the seller agree on a down payment and monthly payment, sign a contract, and you start making payments. The land is yours to use as agreed. It is a simpler, more direct way to buy land, and it puts the power back in your hands.
I have seen people close on a piece of land in a matter of weeks, not months. That speed matters when you have been dreaming of a place for years. It matters when you want to get your kids out of the city and into the woods before they grow up any further. It matters when you are ready to start building your legacy now, not someday.
Is Owner-Financed Land Right for You?
Owner financing is not for everyone. If you have excellent credit and a large down payment, a conventional mortgage might offer a lower interest rate. But if you are like most people I talk to, you are somewhere in the middle. You have a steady job, you can afford a monthly payment, but your credit is not perfect and you do not have twenty percent to put down. For you, owner financing is not a second choice. It is the smartest path forward.
It gives you control. You decide when to buy. You decide what you want to do with the land. You are not waiting for a bank's approval. You are dealing directly with the person who owns the land, someone who has a personal stake in making the deal work. That human element is often missing in modern real estate transactions. It matters.
I have seen people go from renting an apartment and feeling stuck to owning ten acres of pine woods with a creek running through it. They did not win the lottery. They did not inherit money. They simply found a seller who was willing to work with them, and they took the step. That is the power of owner-financed rural land. It turns a distant dream into a real, walkable, ownable piece of ground.
If you are ready to start looking, sites like landandcreek are a good place to begin. They have done the work of finding sellers who offer owner financing. You just have to find the piece of land that feels like home. Once you do, the rest is just a matter of showing up and making the payments. And that, for most people, is a trade they are happy to make.
