Why LandAndCreek Offers a Smarter Path to Rural Land Ownership
For years, the dream of owning a piece of rural land has felt out of reach for many people. Traditional financing demands a pristine credit score, a hefty down payment, and a willingness to jump through hoops that can take months. Meanwhile, the price of raw land in desirable areas has climbed steadily. I have watched friends give up on the idea altogether, assuming that if they could not get a conventional mortgage, they simply could not buy. That assumption is worth questioning.
There is another way to approach land ownership, one that does not require a bank's approval or a perfect financial history. Owner financing has been around for decades, but it is only recently that buyers have begun to see it as a practical, even preferable, path. When I first started looking at rural properties myself, I was surprised by how many sellers were willing to hold the note themselves. It changed the whole calculus. Suddenly, the barrier was not my credit score but my willingness to find the right seller.
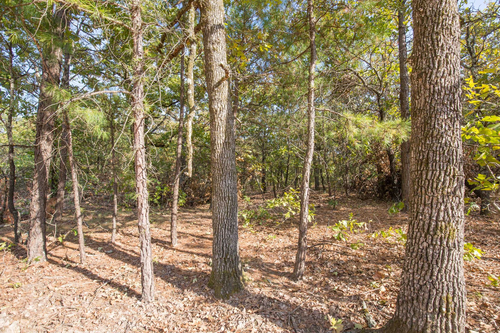
That is where landandcreek comes into the picture. It connects buyers with sellers who offer owner financing on rural land, often with terms that make sense for people who want to build a life away from crowded suburbs. The properties listed there are not cookie-cutter lots. They range from wooded acreage perfect for a weekend cabin to larger tracts suited for off-grid living or small-scale farming. What unites them is the financing model.
How Owner Financing Changes the Game
Owner financing is straightforward in concept: instead of borrowing from a bank, you make payments directly to the seller over an agreed period. The seller retains the legal title until the balance is paid, but you get possession and use of the land from day one. For someone who wants to start building a homestead or simply secure a place to camp and hunt, that access is everything.
The practical advantages are significant. There is no need to wait for a loan officer to approve your application. The seller sets the down payment, often as low as ten percent or less. Interest rates can be competitive because the seller is not subject to the same overhead as a financial institution. And perhaps most important, there is no credit check. For buyers who have rebuilt their finances after a setback, or who simply avoid debt in their daily lives, this opens a door that conventional lending keeps shut.

I have spoken with several people who bought land this way. One couple, both teachers, wanted a piece of forested property in the mountains where they could eventually retire. They had good income but their credit was average, and banks were unwilling to finance raw land at all. They found a seller through an owner-financing arrangement, paid a modest down payment, and now spend every summer weekend clearing trails and building a small cabin. They told me the process took about three weeks from first contact to closing. A conventional loan would have taken months and likely been denied.
What to Look For in an Owner-Financed Property
Not all owner-financed deals are created equal. A buyer should approach any property with due diligence. Here are a few things I have learned to check before signing:
- Verify the legal description of the land and confirm there are no liens or encumbrances. A title search is worth the cost.
- Check local zoning and building codes. Some rural counties have restrictions on structures, septic systems, or road access that could affect your plans.
- Understand the payment schedule and whether there is a balloon payment at the end of the term. Many owner-financed deals are structured with a balloon after five or ten years, so you need a plan to refinance or pay off the balance.
- Ask about access. Does the property have a deeded right of way? Is there a road that is maintained year-round? If the land is landlocked, your plans could be complicated.
These steps may sound tedious, but they are far less painful than discovering a problem after you have already started building. And because owner-financed sales are typically simpler than bank transactions, you can often close faster and with fewer fees.
Off-Grid Living and Building a Legacy
One of the most appealing aspects of buying rural land through owner financing is the flexibility it gives you to build slowly, on your own terms. Off-grid living has moved from a fringe interest to a mainstream aspiration for many families. Solar panels, rainwater catchment, and composting toilets are no longer exotic. They are practical solutions that reduce monthly costs and increase self-sufficiency.
When you own the land free and clear, or even while you are still paying it off, you can start small. Maybe you put in a gravel driveway and a storage shed the first year. The next year, you run a solar system and build a tiny house. Over time, the property becomes your sanctuary, your legacy for children or grandchildren. I have seen families turn a raw piece of land into a weekend retreat that becomes the center of their shared memories.
landandcreek lists properties that are suited exactly for this kind of gradual development. The descriptions often mention recreational use, hunting, camping, or the potential for a homestead. The prices reflect the reality of rural markets, which are generally lower than suburban or urban parcels. And because the financing is direct, you can negotiate terms that fit your cash flow. That is a level of control you simply do not get with a bank loan.
The Trade-Offs You Should Consider
No financing method is perfect. Owner financing has its own risks and limitations. The seller might not be as flexible as you hope. The interest rate could be higher than a bank would offer if your credit is excellent. And because raw land typically does not generate income, you need to be sure you can make the payments without straining your budget.
There is also the matter of due diligence. A bank has a team of appraisers and inspectors. When you deal directly with a seller, that responsibility falls on you. You need to be comfortable reading a survey, understanding property boundaries, and asking the right questions about water rights and easements. If that sounds daunting, you can hire a real estate attorney or a title company to help. It is money well spent.
I have also seen buyers rush into a deal because the terms seemed easy, only to discover later that the property had no legal access or that the soil would not support a septic system. Those mistakes are avoidable with a little patience. The key is to treat an owner-financed purchase with the same seriousness as any other real estate transaction.
Finding the Right Property for Your Vision
The properties on landandcreek tend to fall into a few categories. Some are large wooded tracts ideal for hunting or timber investment. Others are smaller parcels near national forests or rivers, perfect for a weekend getaway. A few have existing improvements like a well or a small cabin. The common thread is that they are offered with owner financing, which keeps the process simple and accessible.
When you browse the listings, think about what you actually want to do with the land. If you plan to build a home eventually, look for parcels with road access and utility proximity. If your goal is recreation, you can be more flexible about location and terrain. Knowing your priorities will help you narrow the options and avoid settling for a property that does not fit.
I have found that the best approach is to visit the land before making an offer. Pictures and descriptions can be misleading. Walking the property gives you a feel for the soil, the slope, the trees, and the neighbors. It also confirms that the access is as described. A weekend drive to see a few listings can save you years of regret.
Owner-financed land is not a shortcut. It is an alternative route, one that requires a bit more personal responsibility but offers a lot more freedom. For anyone who has the patience to learn the basics and the vision to see what a piece of raw land can become, it is a path worth exploring.
